Paying your final home loan EMI can feel like the finish line.
After years of monthly repayments, seeing your home loan balance reach zero is a major financial milestone. But there is one important step you should not overlook: completing the home loan closure process and collecting the right documents from your lender.
Your final EMI payment does not mean you should simply walk away from the bank.
You should confirm that the loan account is properly closed, collect your original property documents, obtain the relevant No Due Certificate or NOC, keep the loan closure letter and final statement, and check whether any applicable mortgage, charge or lien-related formalities have been completed.
Why does this matter?
These documents may become important later if you sell your property, transfer ownership, apply for another loan, refinance the property or need to establish a clear title.
Recent cases also show why borrowers should take this step seriously. In September 2026, the Bombay High Court dealt with a case involving State Bank of India where original title documents deposited as security for a loan could not be traced. The court directed compensation at ₹5,000 per day from December 1, 2023, subject to the conditions of the case, and directed steps for obtaining certified copies and reconstructing the title records. (Source: Bombay High Court, M/s In Vogue Creations v. State Bank of India, September 2, 2026).
In another recent Hyderabad consumer commission case, a lender was ordered to pay compensation after original property documents were not returned following repayment of a housing loan.
The lesson is simple:
Paying your final EMI closes an important financial chapter. But your home loan closure is not complete until you have checked the paperwork and confirmed what happens to your property documents and related security records.
In this guide, I will explain the important home loan closure documents, confirmations and checks you should consider after closing your home loan.
Important: The exact documents and terminology can vary depending on the lender, state, property type, mortgage structure and registration process. If you are unsure about a legal or property-record requirement, confirm it with your lender and an appropriate property or legal professional.
What Happens After Your Final Home Loan EMI?
When you make your final scheduled EMI, the loan is effectively paid off once the lender accounts for the final payment and confirms that there is no remaining amount payable.
But several administrative steps may still follow.
A simplified process looks like this:
Final EMI/payment → loan account settlement → bank confirms zero outstanding → loan closure documentation → release of original property documents → mortgage/charge-related formalities → credit bureau update
The exact sequence can vary between lenders.
This is why you should not assume that the process is finished simply because the EMI has disappeared from your bank account.
Your first objective should be to obtain written confirmation from the lender that the loan has been fully settled.
Your second objective should be to make sure that the original property documents and relevant security/mortgage records are dealt with properly.
Your third objective should be to check whether any charge or lien-related formalities remain.
9 Home Loan Closure Documents and Checks
Some items below are actual documents. Others are important confirmations or checks.
Together, they form a practical home loan closure checklist.
1. Original Property Documents
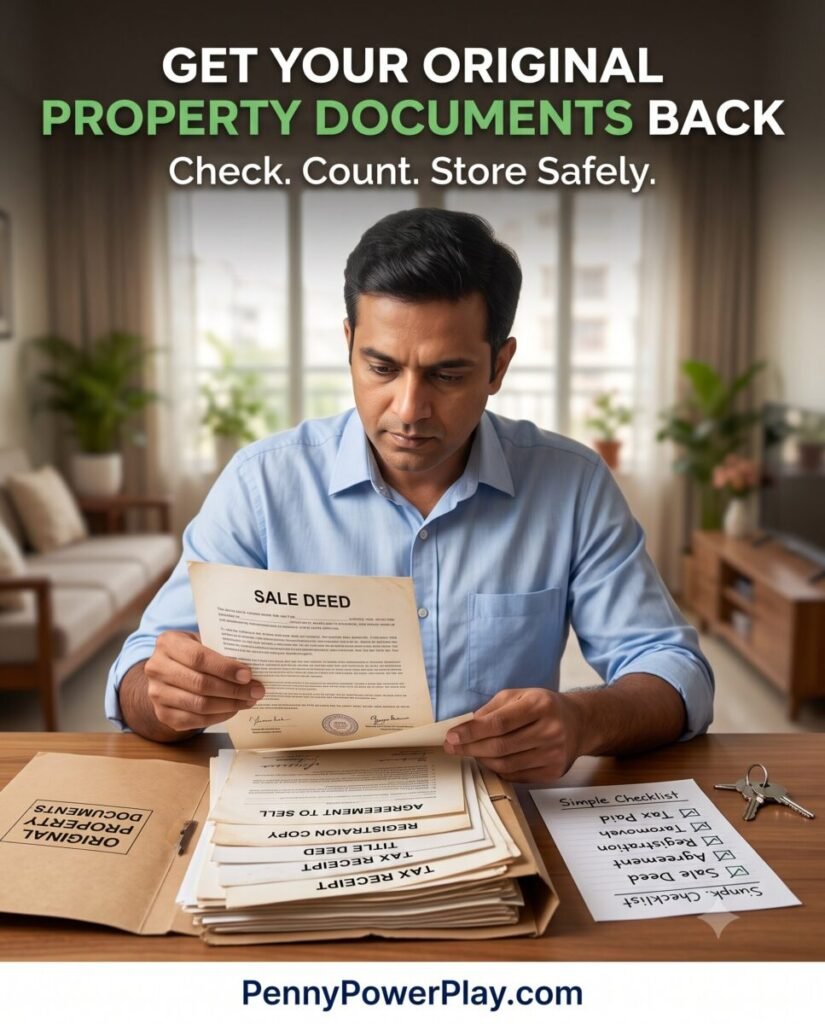
This is one of the most important things to collect.
Depending on the property and transaction, the documents held by the lender may include original title deeds and other property-related documents that were deposited as security for the loan.
Before leaving the bank, ask for the documents that were originally deposited and verify them against the lender’s records.
For example, depending on the transaction, these could include:
- Sale deed
- Agreement for sale
- Previous title documents
- Share certificate, where applicable
- Conveyance-related documents
- Property card or other property records, where applicable
- Development or allotment documents, where applicable
- Other link documents deposited with the lender
Do not assume that receiving one important document means all your original documents have been returned.
Practical tip
Ask the bank for a document list and compare it with the documents you actually receive.
If possible, make a record of the documents received and keep a scanned backup for your personal records.
2. No Due Certificate / No Objection Certificate
Ask your lender for a document confirming that there are no outstanding dues under the home loan.
Different lenders may use different names, such as:
- No Due Certificate
- No Dues Certificate
- No Objection Certificate
- NOC
- Loan closure certificate
The terminology can vary.
The important point is that the document should clearly establish that the loan has been settled and the lender has no remaining claim relating to the loan, subject to the terms of the document.
Do not focus only on the name of the certificate.
Read what the certificate actually says.
3. Home Loan Closure Letter
A loan closure letter provides written evidence that the lender has closed the loan account.
Keep this document safely with your other financial records.
It can become useful later when:
- Selling the property
- Applying for another loan
- Transferring a property
- Explaining an old loan account
- Resolving a dispute
- Checking your credit history
Keep these home loan closure documents safely with your other financial records.
If the lender provides the closure confirmation digitally, save the original email/PDF rather than relying only on access to the bank’s mobile application.
4. Final Loan Account Statement
Ask for the final statement showing that the outstanding loan balance has become zero.
This is different from simply seeing your last EMI deducted from your bank account.
The final statement can help establish:
- Principal outstanding before final payment
- Final payment received
- Interest or other applicable charges
- Final outstanding balance
- Account closure status
Review the statement carefully.
If you see an unexplained amount still showing as outstanding, ask the lender for clarification before assuming the account is fully closed.
5. Mortgage Release Documents
When you take a home loan, the lender generally creates security over the property according to the applicable legal and registration structure.
After the loan is fully settled, the corresponding mortgage/security arrangement may need to be released or recorded as satisfied.
The exact process depends on how the mortgage was created and the applicable state/property-registration system.
Ask the lender:
“Has the mortgage/security interest been properly released or satisfied, and is any further action required from my side?”
Do not assume that every property follows the same procedure.
For some borrowers, there may be registration-related steps or documents that need to be obtained or updated.
6. MODT-Related Documents, Where Applicable
Some home loans involve a Memorandum of Deposit of Title Deeds (MODT) or another mortgage-related arrangement.
The terminology and registration process can vary by state and transaction.
If a MODT or similar mortgage document was created for your home loan, ask the lender what happens to that document after full repayment.
You may need confirmation that the mortgage/security interest has been released or that the relevant record has been dealt with according to the applicable procedure.
Important
Do not assume that every home loan has the same MODT process.
Your lender, property location and manner in which the security was created can affect the procedure.
7. Confirmation of Charge or Lien Satisfaction
Paying off a loan and removing a charge or lien are related but should not automatically be treated as the same administrative event.
Where a charge has been registered with a relevant registry, the lender may have an obligation to take steps to remove or satisfy it.
RBI’s framework specifically covers release of original movable/immovable property documents and removal of charges registered with any registry after full repayment or settlement of the loan account.
Ask the lender:
“Has the charge/security interest been removed or satisfied, and do I need any document or confirmation showing this?”
The answer may depend on the type of property and security arrangement.
8. Check Your CIBIL/Credit Report After Closure
Your home loan is also part of your credit history.
After the lender closes the account, check your credit report after allowing reasonable time for the lender and credit information company to update the account.
Look for the loan account status and make sure it is not incorrectly showing as active or overdue.
Keep in mind that the timing of credit-report updates can vary.
If the account continues to show an incorrect status, contact the lender and follow the relevant dispute-correction process.
Do not make this mistake
Do not assume that because your bank account shows the final EMI payment, your credit report has automatically updated immediately.
Check it.
9. Written Confirmation That Nothing Remains Outstanding
This final check sounds simple, but it is important.
Before you consider the loan closure process complete, make sure you have written confirmation that:
- The loan has been fully repaid
- No principal remains outstanding
- No interest remains payable
- No other loan-related amount remains due
- The loan account has been closed
- The lender has no continuing claim under the settled loan, subject to applicable documentation
This is particularly useful if the loan was closed through foreclosure or a large prepayment rather than through the originally scheduled final EMI.
What Does RBI Say About Returning Property Documents?
This is one of the most important parts of the home loan closure process.
The RBI’s responsible lending framework requires regulated entities to release original movable and immovable property documents and remove charges registered with relevant registries within 30 days after full repayment or settlement of the loan account.
If the delay is attributable to the regulated entity, the framework provides compensation of ₹5,000 per day for the delay.
There is also a specific provision for situations where original property documents are lost or damaged.
In such cases, the regulated entity must assist the borrower in obtaining duplicate or certified copies of the documents and bear the associated costs. An additional 30 days is available for completing this process, with the delay compensation mechanism applying thereafter as specified by the framework.
What does this mean for a borrower?
It means you should take the return of your original property documents seriously.
Do not simply assume: “My loan is closed, so everything else will automatically happen.”
Instead, ask the lender for confirmation.
What If the Bank Cannot Find Your Original Property Documents?
This is one of the situations no borrower wants to face.
But recent cases show that it can happen.
In the September 2026 Bombay High Court case involving SBI, the bank admitted that original title documents could not be traced. The court noted that the bank had a responsibility to preserve and return the documents and directed compensation from December 1, 2023, along with steps to obtain certified copies and reconstruct the title record.
Another 2026 consumer case involved original property documents that were not returned after repayment of a housing loan. The commission directed the bank to return the documents or procure reconstructed/certified copies at the bank’s cost and awarded compensation.
What should you do?
Step 1: Ask for a written response
Do not rely only on a verbal statement such as: “We are checking.”
Ask the lender to confirm the situation in writing.
Step 2: Keep proof of loan closure
Keep copies of:
- Loan closure letter
- No Due/NOC
- Final loan statement
- Payment proof
- Correspondence with the lender
Step 3: Ask for the original document list
Ask the lender to provide the list of documents that were originally deposited or held as security.
Compare this with the documents returned to you.
Step 4: Ask what the bank is doing to locate or reconstruct the documents
Ask specific questions:
- Has the branch searched its records?
- Have the documents been transferred to another branch?
- Have archived records been checked?
- Has an internal investigation been started?
- What is the process for obtaining certified or duplicate copies?
Step 5: Ask about certified or duplicate documents
If the original cannot be found, ask the lender what process it will follow to obtain legally acceptable duplicate/certified documents.
Under the RBI framework, the regulated entity has responsibilities in cases involving loss or damage of original property documents.
Step 6: Escalate through the lender’s grievance mechanism
If the issue is not resolved, use the bank or housing finance company’s formal grievance process.
Keep every complaint number, email and written response.
Step 7: Consider further remedies if necessary
Depending on the facts and the lender involved, borrowers may have regulatory, consumer or legal avenues available.
Because property-title issues can become legally complex, obtain appropriate professional advice before taking major legal action.
Why Are Original Property Documents So Important?
A title document is not simply another piece of paperwork.
Property transactions depend on establishing ownership and title.
If original documents are missing, the problem can become much bigger when you try to:
- Sell the property
- Mortgage the property again
- Transfer ownership
- Obtain another loan against the property
- Complete legal verification
- Establish a clear chain of title
The September 2026 Bombay High Court case is a useful illustration.
The petitioner argued that the missing originals were causing serious prejudice because the properties could not be freely sold or otherwise dealt with. The court recognized the continuing prejudice arising from the loss of documents.
That is why borrowers should treat original documents as an important part of their home ownership records.
What Should You Check Before Selling Your Property After Loan Closure?
Suppose you paid off your home loan two years ago and now want to sell your property.
Do not wait until the buyer’s lawyer asks for the documents.
Check them beforehand.
Your pre-sale checklist
Your pre-sale checklist
- Original title documents available
- Home loan closure letter available
- No Due/NOC available
- Final loan statement available
- Mortgage/security release documentation checked
- Charge/lien status checked where applicable
- Society/property records updated where required
- Relevant property records checked
- Any required lender confirmation available
- Documents organized for the buyer’s legal verification
This can prevent last-minute delays during the sale.
Home Loan Closure vs Prepayment vs Balance Transfer
These three terms are often confused.
Home Loan Closure
The entire outstanding loan amount has been paid and the lender closes the loan account.
This may happen after the final scheduled EMI or after you pay off the outstanding balance early.
Home Loan Prepayment
You pay some or all of the outstanding principal before the scheduled repayment date.
A partial prepayment does not necessarily close the loan.
If you pay the entire outstanding amount early, it may result in foreclosure/early closure, subject to the lender’s process and applicable rules.
Home Loan Balance Transfer
You move your outstanding home loan from one lender to another.
The original lender receives the amount due and closes its loan account, while the new lender creates the relevant security arrangement for the transferred loan.
This is why the documentation process can differ.
Always ask the lender what documents you should collect when the original loan is closed through a balance transfer or foreclosure.
Home Loan Closure Checklist
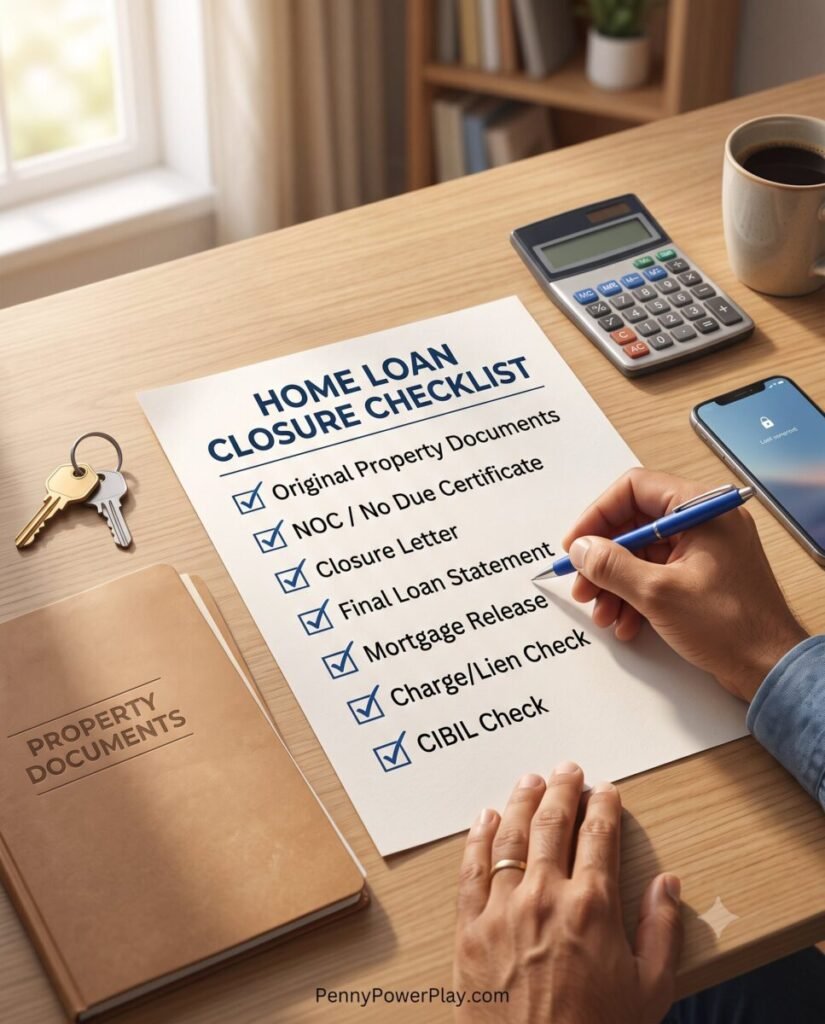
Before you consider your home loan closure process complete, use this checklist:
- Final EMI or final repayment completed
- Final loan statement collected
- Loan closure letter collected
- No Due/NOC collected
- Original sale deed collected
- Other original title documents collected
- Document list checked against documents received
- Mortgage release documents checked
- MODT-related formalities checked, where applicable
- Charge/lien satisfaction checked, where applicable
- Bank confirms zero outstanding
- Credit report checked after reasonable update time
- All documents scanned and securely stored
- Physical originals stored safely
Frequently Asked Questions
1. Is the home loan closed after paying the last EMI?
Usually, the final payment settles the outstanding loan, but you should still obtain written confirmation from the lender and complete the relevant documentation process. Do not rely only on the fact that the final EMI was debited.
2. What home loan closure documents should I collect after closing my loan?
Important documents and confirmations can include your original property documents, No Due/NOC, loan closure letter, final loan statement and applicable mortgage-release documentation. You should also check charge/lien satisfaction and your credit report.
3. How long does a bank have to return original property documents after loan closure?
RBI’s framework requires regulated entities to release original movable and immovable property documents and remove charges registered with relevant registries within 30 days after full repayment or settlement of the loan account.
4. What compensation is payable if the bank delays returning property documents?
Where the delay is attributable to the regulated entity, RBI’s framework provides compensation of ₹5,000 per day. Specific applicability depends on the circumstances and the framework governing the case.
5. What if the bank loses my original property documents?
Ask the bank for a written explanation and a list of the documents that are missing. The RBI framework requires regulated entities to assist borrowers in obtaining duplicate/certified copies and bear associated costs in cases of loss or damage, subject to the framework’s conditions.
6. Should I check my CIBIL report after home loan closure?
Yes. Once sufficient time has passed for the lender’s reporting cycle, check your credit report to make sure the loan account is correctly reflected as closed and does not show an incorrect outstanding balance or overdue status.
Official References
- Reserve Bank of India: Responsible Lending Conduct – Release of Movable / Immovable Property Documents on Repayment / Settlement of Personal Loans
- RBI Handbook on Regulations at a Glance
RBI requirements can depend on the lender, loan, property and applicable circumstances.
Final Takeaway
Paying the final home loan EMI is a major financial milestone.
But do not treat the EMI payment as the only final step.
Before walking away from the lender, make sure you have:
Your original property documents.
Your loan closure confirmation.
Your No Due/NOC.
Your final statement.
Your applicable mortgage-release documents.
Confirmation about charge/lien satisfaction.
And eventually, an updated credit report.
The recent cases involving missing property documents show why this simple checklist matters. A home loan may last 10, 15, 20 or even 30 years, but the property documents connected to it can matter for much longer.
Your final EMI closes a major financial chapter. Make sure your paperwork closes it properly too.
Keeping your home loan closure documents safely can save you significant trouble when you later sell, transfer or refinance the property.
Related Home Loan Guides
If you are applying for, managing or closing a home loan, these PennyPowerPlay guides can help you understand the process:
- Home Loan Application Checklist : Review the documents you may need to prepare before applying for a home loan.
- Home Loan Prepayment & Foreclosure Guide : Understand the difference between prepayment and foreclosure and what to check before closing your loan early.
- Home Loan Balance Transfer : Learn what happens when you move your outstanding home loan from one lender to another and which documents you may need during the process.
- Home Loan Fees and Charges in India : Understand the different charges that may arise during the home-loan journey, including costs that borrowers should check with their lender.
- RBI Home Loan Rules 2026 : Learn about important RBI rules and borrower protections that can affect home-loan customers in India.
- Complete Home Loan Guide for Indian Buyers : Follow this complete guide to understand home-loan eligibility, documents, approval, EMI, disbursement and other important stages of the borrowing process.
About the Author
Ashok Satpute is the founder of PennyPowerPlay.com, helping Indian homebuyers understand home loans, eligibility, EMI affordability, documentation, property costs and borrowing decisions.
He has 8+ years of experience in banking and housing finance, with experience across ICICI Bank, HDFC Home Loans, Axis Bank, DHFL/Piramal Housing and PNB Housing.
His goal is simple:
Help Indian families make better home-loan decisions before they commit to decades of repayment.